


The danger of over-correction: misreading Australia’s real economy
The Reserve Bank of Australia (RBA) stands on the precipice of a historic policy error. As Governor Michele Bullock announced yesterday, the interest rate hike that financial markets had predicted, the central bank’s leadership now risks choking off an economy that is already gasping for air. By stubbornly prioritising a rigid inflation target over the rapidly deteriorating realities of household balance sheets, the RBA board is acting on an outmoded playbook. The assumption that raising the cash rate further is necessary to tame "sticky" domestic demand is fundamentally incorrect—and the consequences for millions of Australians could be catastrophic.
Yet as Bullock, who can slink away and hide, while she enjoys life, in her recently purchased $2 million holiday home in Yamba (just 130 kilometres south of Bryon Bay), families with mortgages consider their plight of being thrown to the financial wolves by our central bank board, who once again has gotten it wrong. But then the relaxing and idyllic, slow-paced lifestyle of Yamba is a far cry from the reality now being faced by tens-of-thousands of struggling families.
It's time Bullock and her board's anachronistic economic policies were abandoned. It's time they pulled their collective heads out of the sand - ostrich tools will not solve outdated fiscal policies.
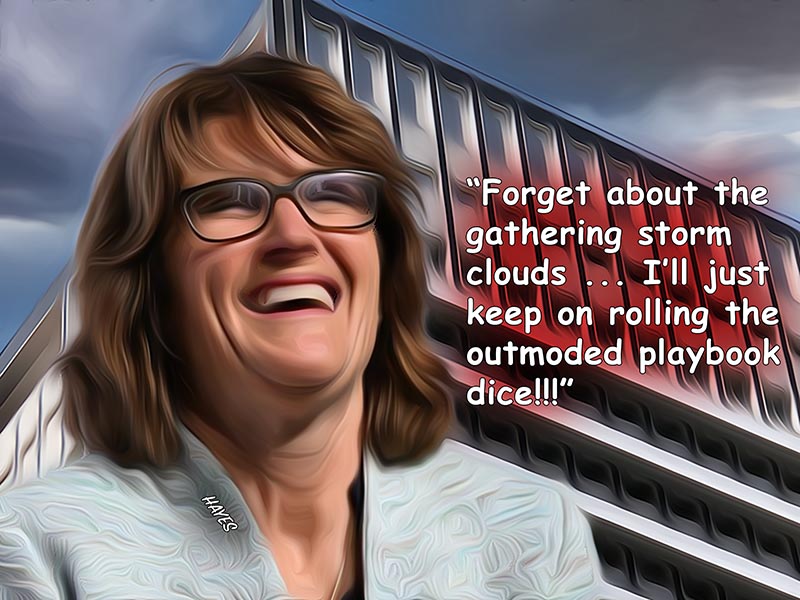
Michelle Bullock and the RBA's outmoded anachronistic economic playbook may well lead to a recession.
30 September 2026
ALAN HAYES
The RBA’s flawed thesis
AT the heart of the RBA’s aggressive stance is a thesis that has increasingly detached itself from the lived experience of ordinary citizens. The board argues that despite multiple rounds of tightening, the domestic economy remains too hot. They point to a historically tight labour market, resilient underlying inflation, and a fear that public inflation expectations could become unanchored.
Michelle Bullock has frequently stated that the risks of inflation remaining above the 2–3 per cent target band are materialising, pointing to service-sector inflation as proof of a resilient consumer. From the ivory tower of Martin Place, the solution seems simple: raise the cost of money, reduce disposable income, and force spending down.
However, this diagnosis mistakes a supply-side structural illness for a demand-driven fever. Australia is not suffering from an excess of consumer exuberance; it is suffering from a series of global and structural supply shocks that interest rates are entirely powerless to fix.
The myth of over-spending
To understand why the RBA’s assumptions are incorrect, one must look at who is actually spending money in the Australian economy. Retail sales figures, when adjusted for inflation and historic population growth, have been flatlining or falling for quarters. The aggregate data used by the RBA hides a deeply fractured society.
Australian households are currently divided into two distinct groups:
- Asset-rich older Australians, who own their homes outright, hold no debt, and are actually benefiting from higher interest rates on their substantial savings.
- Younger families and mortgage holders who are under unprecedented financial distress.
By raising interest rates, the RBA is exclusively punishing the latter group. Working-class families have already slashed discretionary spending to the absolute bone. They are not buying designer clothes or booking luxury holidays; they are skipping meals, delaying dental care, and turning off their heaters - let's not even consider running air conditioners to cope with the predicted El Niño summer.
When the RBA raises rates to cool demand, it is squeezing a sponge that has already been wrung completely dry. The assumption that consumer demand is driving service-sector inflation ignores the reality that many services—such as health, education, and insurance—are non-discretionary. A family cannot choose to stop paying their rising home insurance premium or their children's school fees just because the RBA raised the cash rate.
Squeezing the supply chain
The second fatal flaw in the RBA’s logic is the belief that higher interest rates reduce business costs. In reality, the exact opposite is happening.
The current wave of inflation is heavily driven by rising insurance premiums, soaring commercial rents, high energy costs, and a chronic lack of housing supply. When the RBA raises interest rates, it increases the cost of capital for businesses. A small business owner relying on a commercial loan or overdraft does not suddenly experience lower costs when rates go up; their overheads skyrocket.
To survive, these businesses are forced to pass these higher financing costs directly onto the consumer. In this way, excessive monetary tightening becomes paradoxically inflationary in the short term. It drives up the cost of doing business, which keeps service inflation artificially high, which the RBA then uses as justification to raise rates even further. It is a vicious, self-fulfilling economic cycle driven entirely by central bank dogma that has lost touch with economic reality and creates a predicament that their outdated thinking imposes upon society in general.
The housing crisis: a self-inflicted wound
Nowhere is the RBA's miscalculation more evident than in the Australian property market. Australia is locked in a generational housing crisis, fuelled by a severe shortage of dwellings relative to a surging population.
The only sustainable, long-term solution to housing inflation is to build more homes. Yet, the RBA's high interest rates are the single greatest barrier to new housing construction.
- Developer Insolvencies: The cost of financing residential construction projects has reached prohibitive levels, driving hundreds of building firms into liquidation.
- Deterred Investment: Institutional and private investors are pulling back from new developments because the numbers no longer stack up against high borrowing costs.
- Falling Approvals: Building approvals have plummeted to multi-year lows, ensuring that the housing shortage will worsen.
By keeping the cash rate high, the RBA is actively suffocating the supply of new housing. This drives rents higher, which feeds directly into the Consumer Price Index (CPI). The RBA board is burning down the house to fry an egg, destroying the very capacity the economy needs to naturally lower housing costs over time.
The labour market illusion
The RBA frequently cites the "tight labour market" and low unemployment as a green light for further tightening. This assumption relies on the traditional Phillips Curve—an economic model suggesting that low unemployment inevitably leads to runaway wage growth and demand-driven inflation.
But this model is broken in 2026. Despite low official unemployment, real wage growth in Australia has barely kept pace with inflation over the multi-year cycle. Workers are not enjoying a massive surge in purchasing power. Instead, the low unemployment rate is being artificially sustained by two distinct factors:
- The Second Job Phenomenon: Millions of Australians are taking on second or third jobs just to pay their mortgages, inflating employment numbers while masking deep financial pain.
- Public Sector Growth: A significant portion of recent job creation has been concentrated in non-market sectors like NDIS, healthcare, and government infrastructure projects, which are completely unresponsive to RBA rate hikes.
Crushing the private sector through higher interest rates will not easily shift employment in these public-facing sectors. It will, however, cause a sudden and severe spike in underemployment and job losses among small businesses, pushing vulnerable workers over the edge.
The lag effect and the risk of a hard landing
Perhaps the most dangerous aspect of the RBA’s current strategy is their apparent disregard for the monetary policy lag. It is a well-established economic truth that changes in interest rates take between 12 to 18 months to fully transmit through the economy.
The RBA has already delivered a massive volume of tightening over the past few years. A significant portion of that pressure has still not hit household budgets, as fixed-rate mortgages slowly roll off and business contracts expire. By hiking rates further, Michele Bullock has effectively looked in the rearview mirror to steer a anachronistic economic vehicle moving at high speed.
The central bank risks pushing the Australian economy past its tipping point. Forward-looking indicators—such as consumer confidence, corporate insolvencies, and job advertisements—are all flashing red. If the board continues to hike rates until the backward-looking inflation data finally hits 2.5 per cent, they will have already locked in a severe, self-inflicted recession.
A time for pausing, not punishing
Michele Bullock and the RBA board are fighting yesterday's war with tomorrow's livelihoods. Their assumption that the Australian consumer needs to be disciplined further is wrong. The consumer is already broken. The businesses are already struggling. The housing market is already starved of supply.
True economic leadership requires the courage to look beyond rigid targets and recognise when the medicine is becoming more toxic than the disease - a fact that Bullock and her Scrooge-like board are incapable of understanding. The RBA needs to halt its rate-hiking cycle immediately, allow the lag of previous hikes to wash through the system, and acknowledge that inflation cannot be beaten by destroying the productive capacity of the nation. To do otherwise is not prudent monetary policy—it is economic negligence.
The leadership of the RBA board is severely broken; only a more progressive leadership, in tune with today's fiscal problems, is the answer!




SUBSCRIBE FOR FREE to the Grapevine News Online and to the monthly e-book edition of the Grapevine Community Weekly. Our online news platform and monthly newspaper is about real local news and events. We will not spam you or share your details with third parties.
